Updated September 26, 2026.
Archived article dated February 28, 2025. This dated product update has been edited for clarity. Launch details and roadmap statements below refer to the original publication date; screenshots are historical illustrations. See current membership options and the Mezzi help center for today’s product details.
Use Mezzi AI's new personalization capabilities to start planning for retirement.
To give the conversation more useful context, start with these details:
Set your retirement preferences
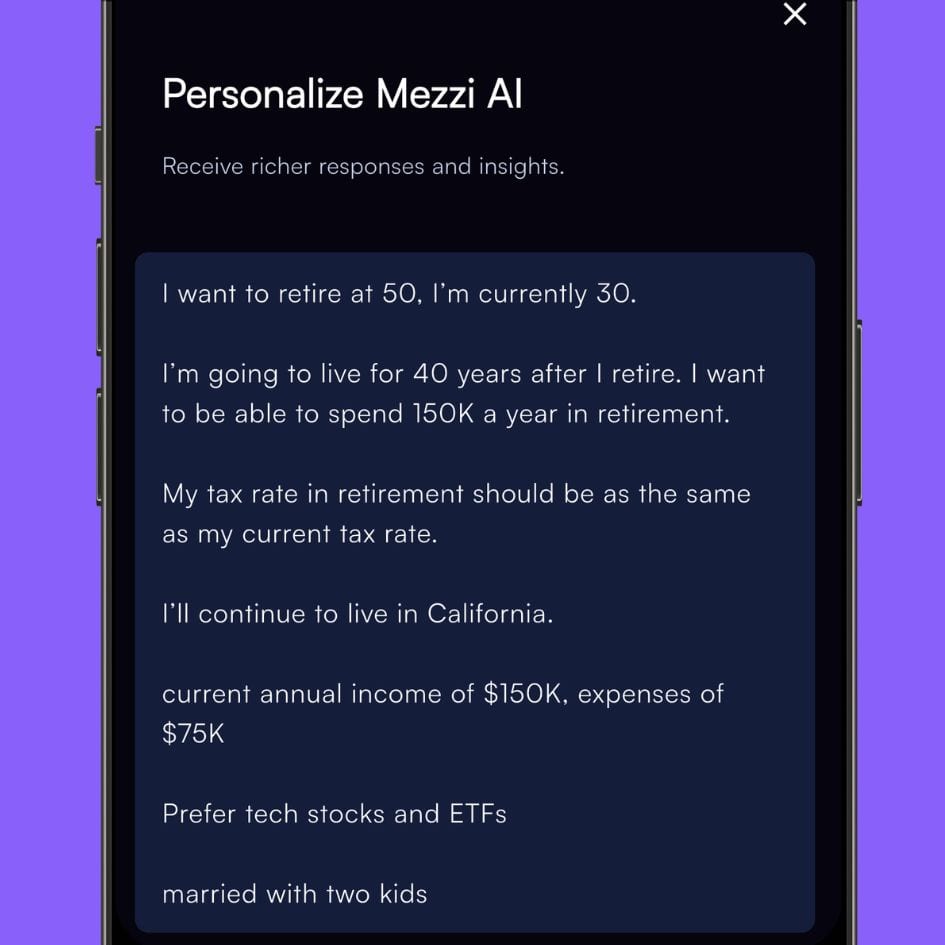
Access personalization from the upper right of your AI Chat tab and enter key details:
- Current age
- Target retirement age
- Expected annual spending in retirement
- Anticipated tax rate in retirement
- Planned retirement location
Include the assumptions you know and mark uncertain numbers as estimates.
Get personalized guidance
With your preferences set, try asking Mezzi AI questions like:
"What are the risks of my current investment strategy for retirement?"
- Identify areas of high risk
- Steps to diversify
"Am I on track to retire at my target age?"
- Determine how much you'll need at retirement
- Get suggestions for optimizing your portfolio allocation
"What should I invest in to boost retirement income?"
- Compare income sources alongside risk, taxes and total return
- Learn about tax-efficient withdrawal strategies
"What should I invest in to retire earlier?"
- Get portfolio rebalancing suggestions
- See how different market scenarios might impact your plan
Keep your plan current
Markets change. Life changes. Tax rules change. Your retirement plan should too. Update your preferences whenever your situation shifts to keep getting relevant guidance.
Pro tips
Ask AI Chat for more detail or specific suggestions. Be sure to update your preferences as your situation changes.
Start with a spending gap, then examine scenarios
For illustration, $80,000 of annual spending less $30,000 of reliable annual income leaves a $50,000 annual gap before any taxes or costs not already included. State whether each number is in today's dollars and whether the income begins at retirement or later. The timing can matter as much as the total.
Ask: “Use these assumptions to compare retiring at 60 and 65. Show contributions, inflation, fees, income start dates and the effect of poor early returns. Tell me what information is missing.” A scenario with a constant return is not a guarantee that the portfolio lasts for life.
What should an answer help you review?
Look for the tradeoffs among spending, saving, retirement date and investment risk. Higher dividend yield alone does not establish a safer retirement income plan, and a projection does not make an illiquid asset available for withdrawals.
Use the output to refine your questions and coordinate with qualified professionals where needed. The launch described conversational planning, not a certified retirement-income result or automatic withdrawal service.
Explore the current experience in your own account, or check the Mezzi help center for current setup and availability.
Open MezziBy Manish Jain, CFA, co-founder of Mezzi. Original publication date retained; editorial clarification September 26, 2026.
This historical product update is for informational purposes. Examples are illustrative, not investment recommendations or promised results. Account coverage and data quality affect analysis. Review assumptions before acting; AI can make mistakes.