The BoostMezzi’s Sunday email about one decision shaping your wealth.
Your tax return shows what you owe—and how your investments affect your wealth.
Some CPAs have limited time for investment strategy, or see it as outside their role. As one member shared with me:
“Our CPA handles the filing. But when we ask about tax strategy, we don’t get answers or guidance on where to turn. We’re willing to pay for advice. We just weren’t told what help was available.”
Why do you need such guidance? These four scenarios show what your return can reveal.
1. You didn’t sell. You still owe.
Mutual funds hold collections of investments. When a fund sells some at a profit, it may distribute those profits to shareholders, often near year-end.
Outside a retirement account, you can owe tax even if you kept your shares and reinvested the payout. The IRS explains how mutual fund distributions are reported.
Worth considering: Am I paying unexpected tax on my mutual funds? Could I reduce future taxable distributions, and what would the tradeoffs be? Selling an existing fund can itself trigger tax, so a switch is not automatically a saving.
2. Same dividend. Different tax bill.
Some of your investments likely pay dividends. Some payments are labeled qualified, while others are non-qualified. That distinction can make a meaningful difference to your tax bill.
Qualified dividends generally receive lower federal capital-gains rates. Non-qualified dividends generally face ordinary income rates, like salary. Eligibility rules, including holding periods, matter.
Look into: Could changing my dividend-paying investments, or the accounts I hold them in, help me keep more after tax? Consider investment goals, risks, fees, taxes from selling and account restrictions together.
3. More income. A higher tax rate?
Non-qualified dividends, taxable interest and profits from selling investments held for a year or less can add to income taxed at ordinary rates.
Federal tax brackets work in layers. Only the income in a higher layer gets that higher rate.
Qualified dividends and most profits from selling investments held longer than a year use separate rates, which also depend on your taxable income. The IRS explains the distinction between short- and long-term gains.
Understand this: Your top tax bracket is not the rate you pay on every dollar. How did investment income affect your tax calculation, and which choices are worth reviewing?
4. Are those losses still available?
Losses can reduce the bill too. Selling an investment at a loss outside a retirement account may offset investment profits. A drop in value alone does not count.
Unused net capital losses may carry forward to future tax years. Deduction limits and wash-sale rules can affect the amount available; the IRS’s investment income guidance explains the rules.
Look into: How much of your investment losses was used, and how much remained? Check the return and supporting carryover calculations rather than assuming the remaining amount.
Put your return to work with Mezzi
Connect all your investment accounts and update your Financial Profile. Choose a question below, then upload your 2025 tax return in that chat to explore last year’s reporting alongside what you own today.
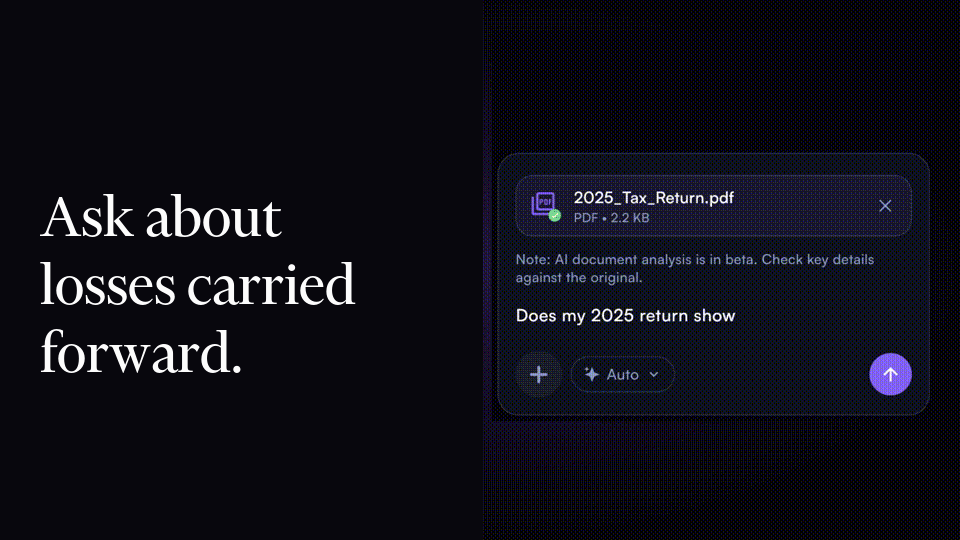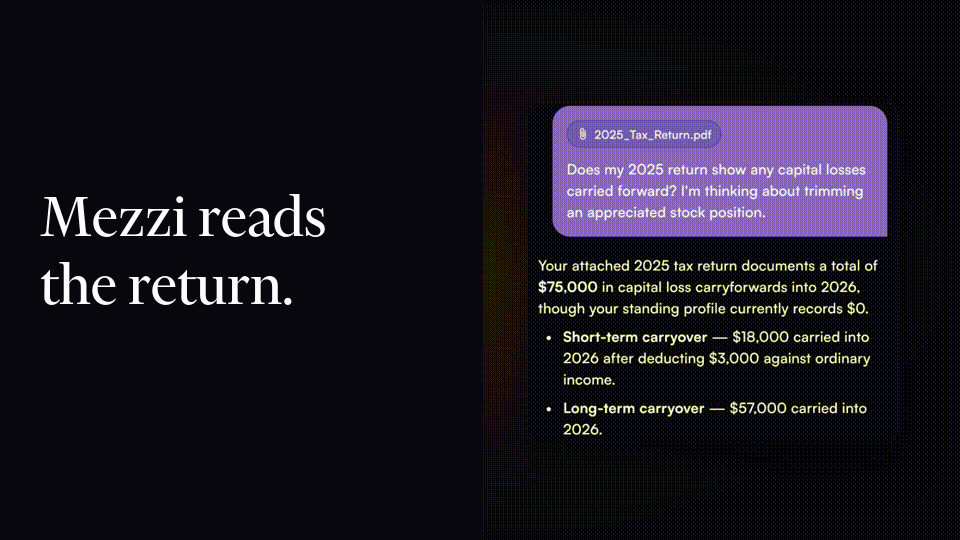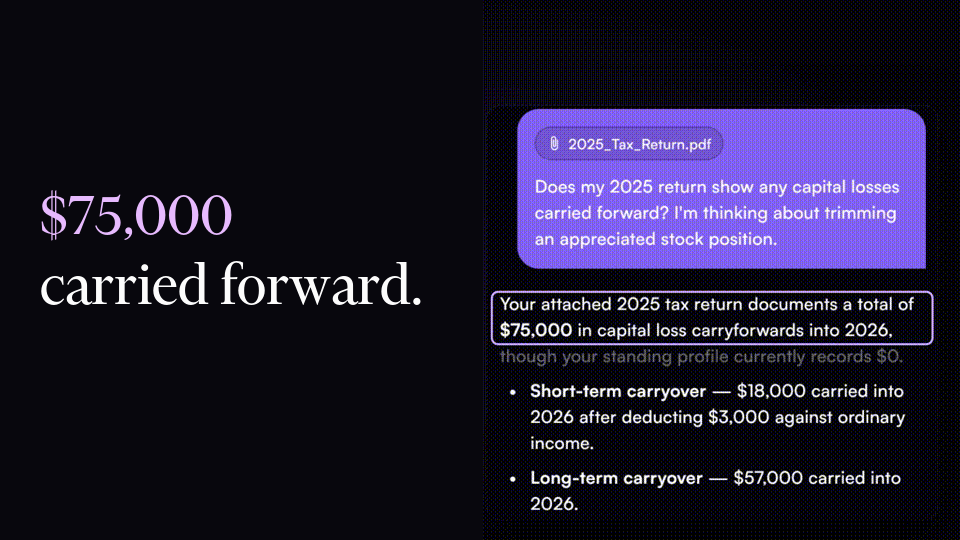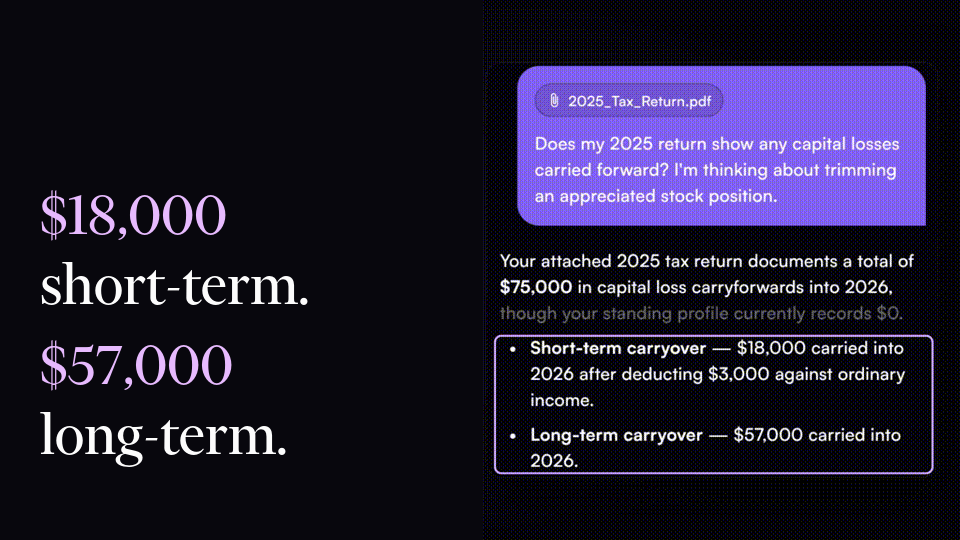
Ask Mezzi
What does my tax return reveal about the investments I own today?
Put my return in contextStart with a specific question, then upload your return:
Current holdings do not verify last year’s transactions. Include supporting documents when needed and confirm the analysis before acting.
Your return is more than a record of last year’s taxes. Use it to ask better questions about the investments you own today.